 PTEN
A little more oil, a lot more optimism
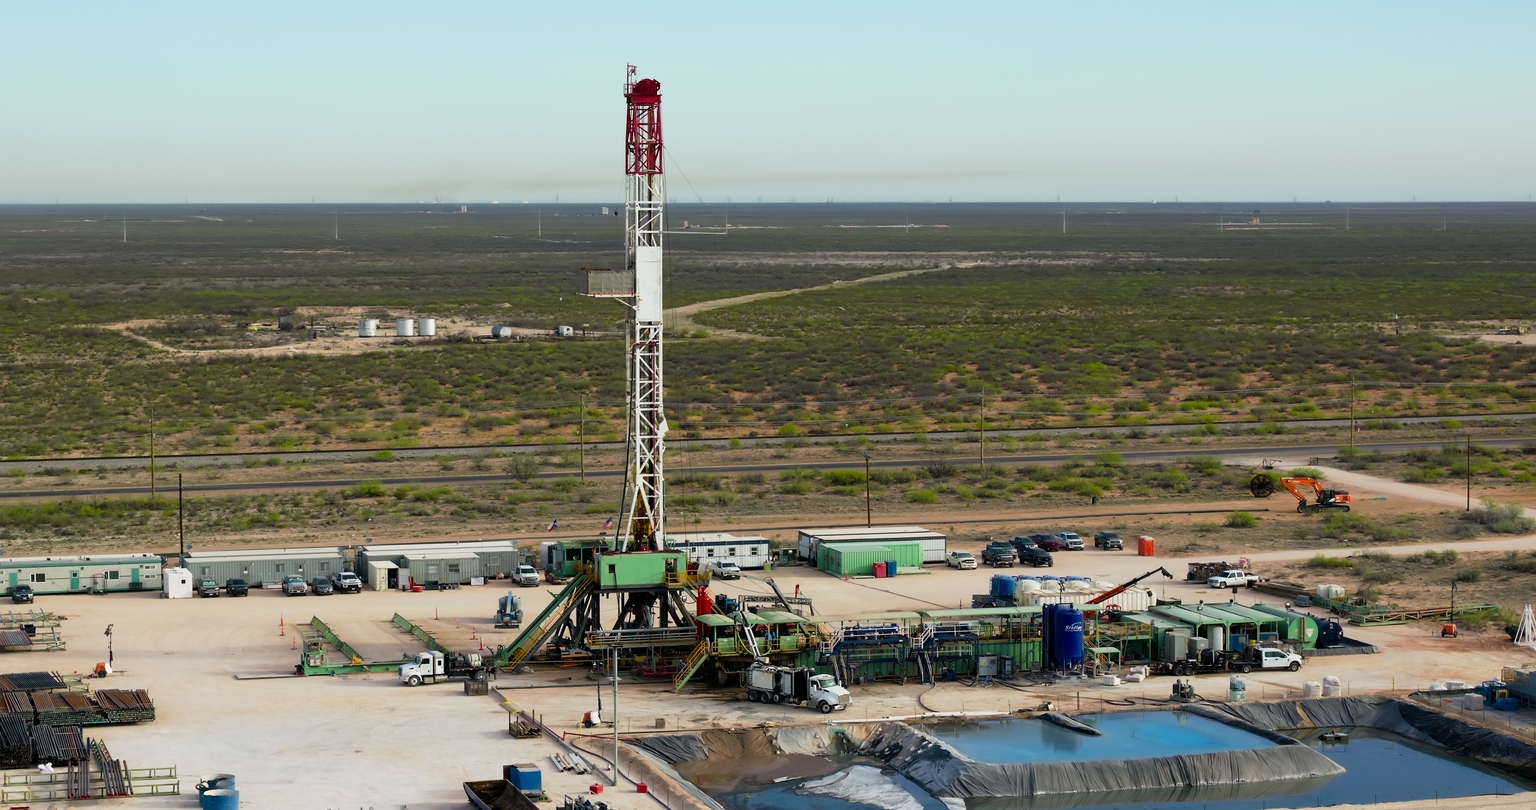
Patterson-UTI just got the kind of rating upgrade that makes Wall Street perk up like it heard free bagels. The bullish call hinges on a simple story: North American oil supply is tightening, drilling activity is picking up, and PTEN is sitting right in the sweet spot with exposure to both drilling and completions.
Why PTEN is on the nice list
The thesis isn’t exactly rocket science, but it is investor-friendly:
- oil market tightness is supporting more drilling demand
- the company’s dual business mix gives it more ways to benefit
- the NexTier acquisition is still padding the setup
- EBITDA could keep growing faster than the market expects
That’s the kind of combo that can keep an earnings cycle alive longer than skeptics would like.
Cheap for a reason — or cheap before the rerate?
The stock is trading at about 4.65x forward EV/EBITDA, which is a fancy way of saying the market still isn’t paying up for the story. Bulls would argue that’s the opportunity: if the current tightness in oil markets sticks around, the valuation could look pretty sleepy in hindsight.
Big picture: this is one of those classic cyclical calls where the numbers matter, but so does the vibe. If North American oil stays in demand, PTEN could keep riding the wave instead of paddling against it.